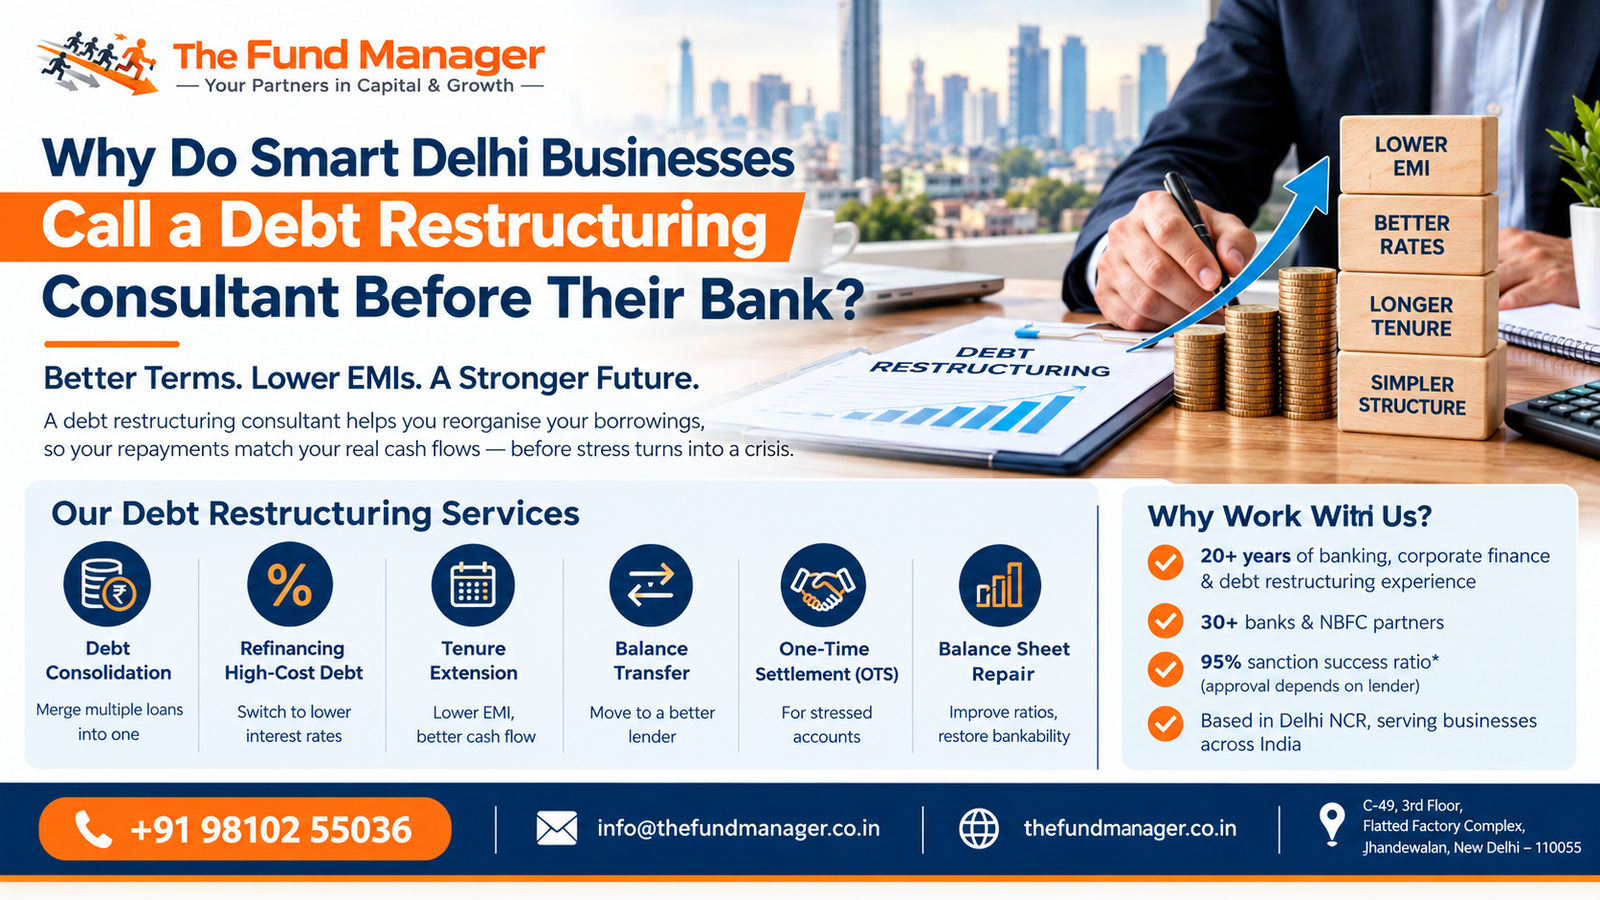
When EMIs start to pinch, most promoters walk into their bank and ask for relief. Many come out with a “no”, or with terms that make the problem worse. A debt restructuring consultant in Delhi gets involved earlier. The reason is simple: lenders approve what they can understand, and a stressed loan book rarely looks understandable on paper.
Why Does Timing Matter in Debt Restructuring?
Because your options shrink as stress grows. A business with regular repayments can usually pursue consolidation, refinancing or a balance transfer. Once accounts turn stressed, the conversation shifts towards One-Time Settlement (OTS) and compromise settlements, which are harder and costlier.
A debt restructuring consultant in Delhi helps you act while the choices are still wide. Our firm’s rule of thumb is to start with a debt map (lender, rate, EMI, security, tenure) before anyone approaches a lender.
Why Is NBFC and Unsecured Debt the Usual Starting Point?
Rapid growth often leaves a business with high-cost NBFC loans, unsecured borrowings and short tenures. Short tenures mean large EMIs, and large EMIs eat the working capital the business needs to grow. Restructuring replaces that patchwork with a cheaper, longer and simpler structure.
Where collateral exists, unsecured debt can be refinanced into a secured, longer-tenure loan at lower cost. This is one of the most common routes a business loan restructuring consultant evaluates.
Why Should a Business Loan Restructuring Consultant Have a Banking Background?
Because restructuring is a negotiation, and the other side is a credit committee. People who have sat on that side know what it takes to say yes.
Ritesh Sharma has 20+ years in banking, corporate finance, debt restructuring and capital markets. His work covers structuring debt around cash flows, negotiating OTS and compromise settlements with banks and NBFCs, and evaluating resolution strategies for stressed accounts.
Shailendra Dixit brings 18 years of SME and Business Banking experience across IndusInd Bank, Kotak Mahindra Bank, ING Vysya Bank, Barclays Bank and Standard Chartered Bank, including accounts of ₹10 crore and above. He knows the questions a credit team will ask, and he helps you answer them before they are asked.
Their full profiles are on our About Us page.
Why Does Repayment Need to Follow Cash Flow, Not the Other Way Round?
A loan that looks fine on a sanction letter can still fail if it ignores your cash cycle. A trader paid in 90 days cannot service a 30-day-style EMI pattern. Our approach designs repayment from your actual cash flows, then maps lenders who can support it. That is why the diagnostic call comes first and covers your business, cash cycle and funding need.
For businesses whose fundamentals support it, Ritesh also builds a medium-term debt-reduction roadmap, with a potential horizon of roughly 5–7 years.
Why Restructuring Alone Is Not Enough: The Balance Sheet Angle
Even a good restructuring proposal can stall if the balance sheet is weak. Lenders look at ratios, related-party dealings and DSCR (debt service coverage ratio). That is why our work often includes balance sheet structuring, which covers bankability, related-party clean-up and credit rating advisory. Fixing the ratios first tends to improve the terms you are offered.
Why Work With a Debt Restructuring Consultant for Companies in Delhi NCR?
A debt restructuring consultant for companies in Delhi NCR is close to your lenders and your market. We work with businesses in Delhi, Noida, Gurugram, Faridabad and Ghaziabad, and across India. We serve MSMEs, mid-market firms and large corporates, typically those with established operations and audited financials. Our network includes 30+ banks and NBFC partners, so the lender is matched to your profile instead of found by trial and error.
Our Process in Five Steps
Diagnostic call: business, cash cycle and funding need.
Financial structuring: numbers aligned with bank credit norms.
Lender mapping: the right bank or NBFC.
Sanction and negotiation: best available rate and terms.
Disbursement and support: until funds are credited.
You can see the full flow on our Our Process page and visit our Debt Restructuring page for service details.
Conclusion: Why Wait Until the Debt Becomes a Crisis?
The best time to speak to a debt restructuring consultant in Delhi is while your repayment record is still clean. Early, you can compare consolidation, refinancing, tenure extension and balance transfer. Late, you are often negotiating a settlement. A short diagnostic conversation will show you where you stand, with no obligation and no promise of guaranteed approval.
Book a confidential consultation: Debt Restructuring Consultant | +91 98102 55036 | info@thefundmanager.co.in | C-49, 3rd Floor, Flatted Factory Complex, Jhandewalan, New Delhi – 110055